
Car
Insurance agent's error in a car policy
What was examined: the age and driving-experience restriction in the policy, the agent's error and the insurer's liability.
Read the case (in Hebrew) →Sassi Lev | Attorney for property insurance claims
Representing private and business clients in car, home and business insurance claims against insurers. When there is a dispute over coverage, the extent of the damage or the amount paid, we review the documents and plan the next step.
Claim denied? Only part paid? Payment delayed?
Hand over the document.
Car, home and contents, water damage, property damage and third-party claims.
Review my case →
Fleet damage, third-party claims, assessment deductions and vehicle downtime.
Review my case →
Cargo and heavy-vehicle damage, liability and coverage disputes.
Review my case →
Disputes over parts, price lists, arrangements and payment deductions.
Review my case →
Accidents, total loss, theft, diminished value and assessment gaps.
Learn more →
Fire, water, plumbing, structure and contents.
Learn more →
Building, equipment, stock and business property damage.
Learn more →
Buildings, equipment, vehicles and other property.
Learn more →
Coverage, source of the damage and scope of repair.
Learn more →
Disputes over liability and the extent of damage.
Learn more →A denial, a partial payment or a delay is not necessarily the end of the process.
Send the letter or the payment noticeWe review the argument, the policy and the facts behind it.
We check what was deducted and how the payment was calculated.
More than 30 days? We review the timeline, the requests and the documents.
We don't start with a letter. We start by understanding the case.
Send documents for reviewDenial letter, payment notice, assessor's report or correspondence, on WhatsApp.
Policy and coverage, the reasons for denial, the assessor's report and the actual calculation.
What is strong in the case, what is missing and what the possible steps are.
A reasoned demand, completing the evidence and, if needed, legal proceedings.
Against the insurer and in court, until the case is closed.
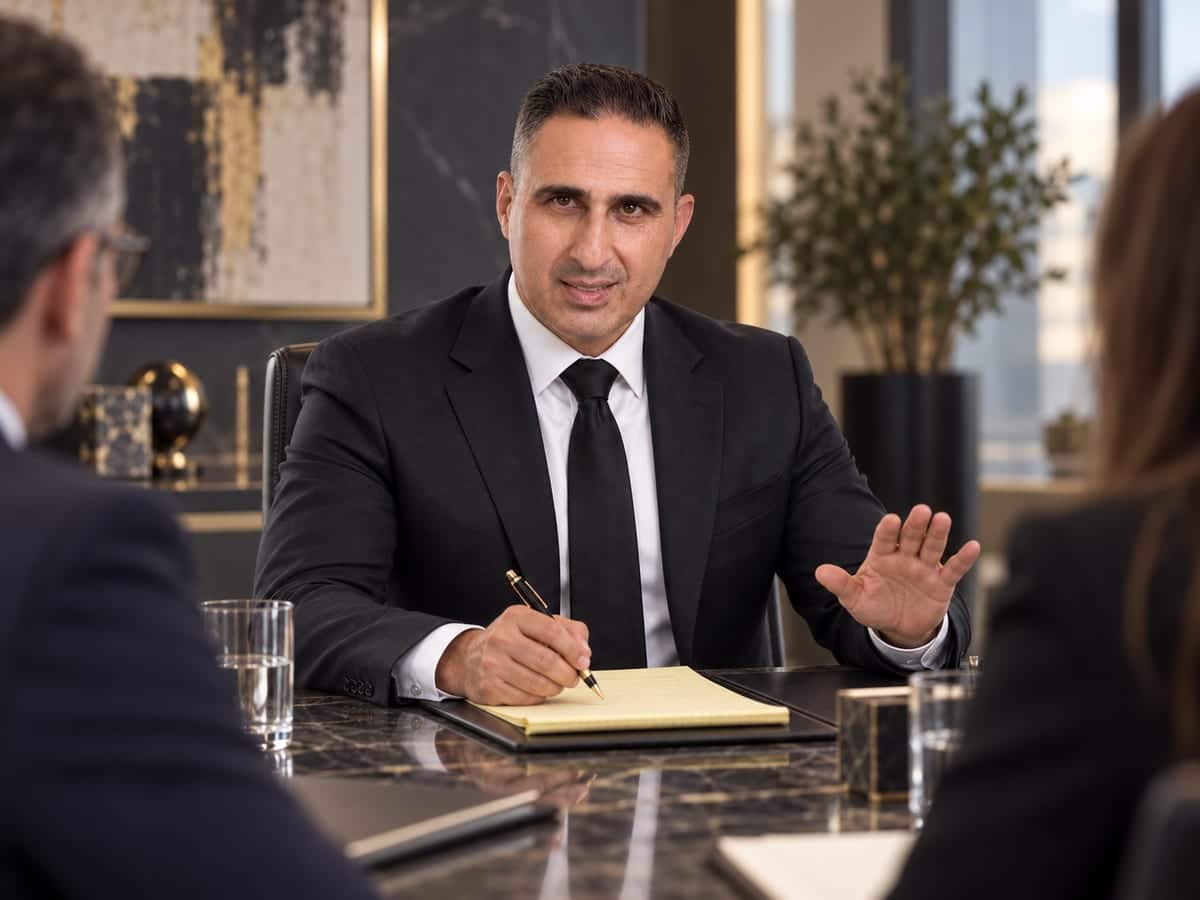
Sassi Lev, an attorney representing policyholders in car, home and business claims against insurers.
The Sassi Lev law office represents policyholders and business clients in property insurance claims and property damage. The work includes reviewing policies, denial letters and payment notices, working with assessors and other professionals, and conducting legal proceedings where needed.
Adv. Sassi Lev heads the firm. He holds a master's degree in commercial law, with honors, from Tel Aviv University.
He completed his legal internship at the court and then represented insurers and corporations in court. That is the source of his in-depth knowledge of insurance and tort law, alongside extensive litigation experience before courts at every level.
In property insurance claims, the gap between what the policyholder expects and what the insurer offers usually forms in three places: how the policy is read, the extent of the damage set in the assessment, and the calculation that follows from both. The firm works on all three in parallel, not only on the last letter received.
Throughout the case, the client knows who is handling it, where it stands and what the next step is. Messages come in directly on WhatsApp, and correspondence with the insurer is managed by one person at the firm. This is not a promise of an outcome. It is a promise that the case will be run in order, on time and on the right facts.
 Trust seal
Coverage. Damage. Evidence. Strategy.
We read the policy, its clauses and extensions, and check what is actually covered and what the insurer's position rests on.
We compare the extent of the damage with the assessor's report: repair items, price lists, diminished value and the deductions made.
We collect and organize the material: documents, photos, correspondence and a timeline, and identify what is missing to support the claim.
We set the course of action against the insurer: a reasoned demand, negotiation or legal proceedings, depending on the circumstances.
What was examined: the age and driving-experience restriction in the policy, the agent's error and the insurer's liability.
Read the case (in Hebrew) →
What was examined: the source of the damage, the coverage question and the scope of repair.
Read the case (in Hebrew) →
What was examined: building, equipment and stock against the policy terms and requirements.
Read the case (in Hebrew) →What was examined: the type of parts, the deduction made and its basis.
Read the case (in Hebrew) →
What was examined: the electrical breakdown exclusion, the source of the damage and the extent of harm to the battery.
Read the case (in Hebrew) →
What was examined: the disclosure notice, the expected deduction rate and the calculation behind it.
Read the case (in Hebrew) →
What was examined: the reason given in the denial letter, the license restriction and the causal link.
Read the case (in Hebrew) →
What was examined: the presumption of delivery of the suspension notice and the validity of the insurance cover.
Read the case (in Hebrew) →A property insurance case opens with the same four checks, whether it involves a car, a home or a business. This is what happens after the documents arrive and before a single word is sent to the insurer.
What is included, what is excluded and which exclusions were applied. In property policies, the difference between coverage and exclusion often turns on a single phrase. We check the wording that applied on the date of the event, the extensions actually purchased, and whether the exclusion relied on was properly highlighted.
The insurer's assessor's report is an opinion, not a ruling. We compare it with the damage records, the repair quotes and the actual cost of repair. Where the gap is material, a counter-report on the client's behalf is considered.
A denial letter must state the reason and the clause it relies on. A partial payment often comes with deductions that were not explained. We read the letter against the policy and the evidence, and check whether the reason holds.
In an insurance claim, deadlines run from two directions: from the date of the event and from the date of the insurer's answer. We build a full timeline and identify what has already closed, what is still open and what needs action now.
An insurance claims lawyer steps in once the documents exist. A letter, an assessor's report, a policy or correspondence that has stalled. Hand it over. From here, it's on me.
Short answers to common questions about insurance claims. Denial letters, partial payments, assessments, documents and release forms are among the topics that come up at the start of a claim.
Yes. A denial letter is the insurer's position, not a ruling. We check the argument against the policy and the documents, and decide how to proceed.
We compare the assessor's report, the policy and the amount actually paid, and check what was deducted and on what basis.
The policy, the denial letter or payment notice, the assessor's report and your correspondence with the insurer.
Signing a release usually closes the claim. It is worth checking what it means before you sign, not after.
As soon as you receive a denial letter or a partial payment, or when handling is delayed beyond a reasonable time.
The assessment can be examined against the actual damage. We compare the items, the price lists and the assumptions behind the calculation and, if needed, obtain a second opinion.
It depends on the type of damage, the volume of documents and how much is in dispute. A well-documented case shortens the process; a dispute over coverage or the assessment lengthens it.
In a third-party claim we examine liability for the event and the extent of the damage. We gather records from the scene, the parties' details and professional opinions, and approach the insurer of the party responsible.
No need to start with a long form. Start with what you already have.
The denial letter, the payment notice, the assessor's report, photos or your correspondence with the insurer are the starting point for the review.