Adv. Sassi Lev | Property insurance claims and torts | Car · Home · Business | Claims management for companies
Adv. Sassi Lev | Property insurance claims and torts
077-444-7050|sassi@lev-lawfirm.com|Leonardo da Vinci 14, Tel Aviv
Sassi Lev Law Office
Home / Private clients/Third-party claims
Private track

Third-party claims

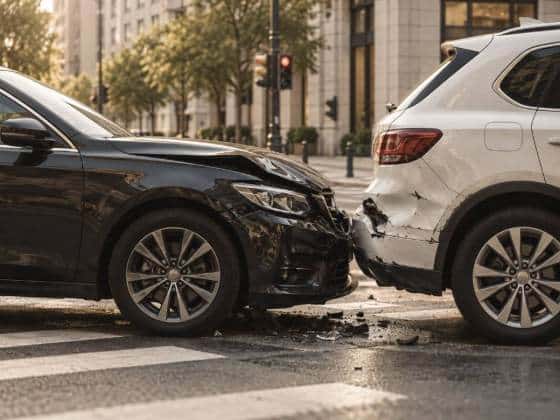
Someone else damaged your car or your property. In a third-party claim you deal with the other side's insurer, and the dispute turns on liability and the extent of the damage. We gather the records and check the answer you received.

Selected area

Third-party claims

When someone else caused the damage, you deal with the other party's insurer. The dispute concerns liability, the extent of the damage, and sometimes both.

  • Disputes over how liability is divided
  • Dispute over how the event happened
  • Partial payment with no explanation
Third-party claims
Where it gets stuck

Three situations. The same starting point.

01

The claim was denied

The letter cites a policy clause and sounds final. It is usually written in general terms and does not address what actually happened to you.

What we do about itWe read the stated reason against the policy wording and the facts of the event, and check whether the clause applies here at all.

02

They paid, but less

The amount you received is lower than the assessment, and the deductions appear as a single line with no breakdown.

What we do about itWe compare the report with the payment item by item, and ask for a written explanation of every reduction.

03

The payment is not coming

Weeks have passed, every request ends with a demand for another document, and the file is not moving.

What we do about itWe build a timeline of what was requested and what was actually provided, and set a deadline for a written answer.

What to send

Documents for the review

You do not need to complete everything in advance. Send what you have, and we will tell you if anything is missing.

Send documents
  • ✓Details of the event and the parties
  • ✓An assessor's report
  • ✓Photos and videos
  • ✓Correspondence with the other party's insurer
How it works

What happens once you send it

01

Sending the documents

On WhatsApp or by email, no long forms.

02

Reviewing the file

Coverage, the reasons for denial and whether they fit the facts.

03

A clear picture

What the financial gap is and which route fits.

04

Dealing with the insurer

We take over the dealings. You stay informed.

Disputed liability examined through the records
Case from the field

Disputed liability examined through the records

The other party disputed how the event happened. Compiling the records and comparing them with the assessor's report shifted the discussion.

Figures worth knowing

Three facts worth knowing before you decide

30 days The time within which an insurer must pay benefits that are not in dispute
3 years The shortened limitation period that applies to insurance claims
1 document All it takes to start a review: the denial letter or the policy
Glossary

Terms that appear in letters from the insurer

Many disputes start with a term nobody explained. These are the terms that come up in almost every private property insurance file.

Policy exclusion

A clause that removes a specific event from the cover. An exclusion must be clearly highlighted in the policy, and whether it applies is examined against the specific facts of the event.

Non-disclosure

A claim that material information was not provided when the policy was taken out. We check what was actually asked, how the question was worded, and whether it relates to the damage.

Underinsurance

A sum insured lower than the value of the property. The benefit is reduced proportionally, and the claim is checked against the proposal form you signed.

Release and discharge form

A document that closes the claim. Signing it greatly limits what can be done afterwards. It is worth checking before you sign.

Diminished value

A separate damage item for cars. In many cases it is not included in the first payment and has to be claimed explicitly.

Special interest

A financial sanction the court may impose on an insurer that did not pay benefits that were not in dispute.

Where we work

Representing policyholders across Israel

The office is in Tel Aviv and represents private clients in every court district in Israel. Most of the work is handled digitally, and court appearances take place in the court that hears the case.

You do not need an in-person meeting to start. Sending the documents on WhatsApp or by email is enough for an initial review.

Leonardo da Vinci 14, Tel Aviv · 077-444-7050

Gush Dan and the Center Tel Aviv, Ramat Gan, Givatayim, Herzliya, Petah Tikva, Rishon LeZion
Sharon and Shfela Netanya, Kfar Saba, Ra'anana, Rehovot, Ness Ziona, Ashdod
Jerusalem area Jerusalem, Mevaseret Zion, Beit Shemesh, Ma'ale Adumim
North and South Haifa, the Krayot, Afula, Nazareth, Be'er Sheva, Ashkelon, Eilat

Representative cases

Files that began with a negative answer

Three cases that show where the gap opened and what changed it. No names, and no figures that cannot be verified.

Car insurance

A denial that did not fit the event

The situation

The letter cited a policy exclusion and stated that the event was not covered. The client had already assumed the file was closed.

What was done

Reading the exclusion against the circumstances of the accident showed it did not apply here. The renewed request relied on the wording of the policy itself.

Water damage

Repairs that stopped halfway

The situation

A provider on behalf of the insurer fixed the source of the leak, but the moisture damage to the walls and floors was left open.

What was done

Comparing the moisture inspector's report with the work actually done brought the file back for discussion.

Home insurance

Contents worth more than what was recorded

The situation

The contents were valued as a blanket list, without regard to the items that were actually in the home.

What was done

Gathering records, photos and supporting documents set a different basis for discussing the value of the contents.

The descriptions are general and do not identify any file or client. The outcome of one case does not indicate the outcome of another.

FAQ

The other party's insurer is not answering. What can be done?

+

A structured request with full documentation and a deadline is the first step. After that, legal proceedings are considered.

Can I claim even if I am not insured?

+

Yes. A third-party claim does not depend on you having a policy.

I was found partly at fault. Is that final?

+

No. The division of liability is examined against the records and can change.

File review

Start with the document you already have.

Send the denial letter, the payment notice or the policy, and we will come back with a clear picture.

Send it on WhatsApp
Read before you act You received a denial letter. What now?→ Partial payment: where the gap opens→ Release and discharge form: what you are signing→