
Adv. Sassi Lev | Property insurance claims and torts | Car · Home · Business | Claims management for companies
Adv. Sassi Lev | Property insurance claims and torts
077-444-7050|sassi@lev-lawfirm.com|Leonardo da Vinci 14, Tel Aviv
Sassi Lev Law Office
Home / Business clients/Business insurance claims
Business track

Business insurance claims

Building, equipment, stock and business interruption. In a major event the gap usually forms in the assessment, in the stock valuation and in deductions that repeat from claim to claim. We review the policy and the figures behind the payment.

Selected audience

Businesses and buildings

Building, equipment and stock insurance. In a major event the dispute is usually about the extent of the damage, the value of the stock and business interruption losses.

  • Stock and equipment value against the valuation
  • Business interruption and loss of profits
  • Underinsurance claims
Businesses and buildings
Three places money leaks

Where the money erodes, and how to stop it

01

A reduction that repeats in every event

A wear-and-tear deduction, a parts price list or a garage difference. In a single file it looks negligible. Across hundreds of events it is a budget line.

The action requiredWe map the reduction pattern across events and set it against the policy wording, instead of arguing file by file.

02

Operational damage that is not counted

Downtime days, a replacement vehicle and lost output are not part of the assessment, and so they are not part of the claim either.

The action requiredWe document the downtime period and the actual loss, and include them in the claim as a separate damage item.

03

Files forgotten along the way

Third-party claims and open files that close without follow-up, because nobody holds the full picture.

The action requiredOne intake channel for every event, with a central status that shows what is open, what is stuck and what is closed.

Starting point

How we start working together

A short scoping call and a map of your existing insurance portfolio. Your agent stays in place. Only who manages the disputes changes.

Schedule a call
  • ✓The business policy and its annexes
  • ✓The insurer's assessor's report
  • ✓Stock records and supporting documents
  • ✓Records of the event
How it works

A working model for managing claim volume

01

Mapping the insurance portfolio

A review of the policies, the arrangements and the current procedure.

02

One reporting channel

A single intake point for every event, with a fixed list of documents.

03

Ongoing management

Dealing with the insurer in every file.

04

Periodic reporting

A consolidated status: files, amounts and trends.

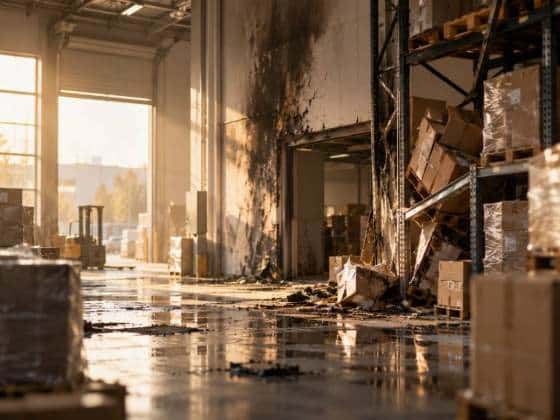
Warehouse fire: a gap addressed through stock records
Case from the field

Warehouse fire: a gap addressed through stock records

The initial stock valuation did not reflect the actual inventory. Orderly supporting documents changed the scope of the benefits under discussion.

Scale

The scale of centralized management

30 days The time within which an insurer must pay benefits that are not in dispute
1 channel One intake point for all damage events, instead of dozens of separate requests
4 stages From mapping the insurance portfolio to consolidated periodic status reports
What is checked in every event

The six recurring checkpoints in a business file

In business files the loss builds up from the same reductions repeating across many events. These are the points checked routinely in every file that enters the channel.

Wear-and-tear deductions

A blanket deduction for wear and tear. We check whether it is grounded in the policy and proportionate to the part that was replaced.

Parts price lists

A gap between the price list the insurer uses and the actual cost of the part, including original and alternative parts.

Contracted garage

A reduction on the grounds that the repair was done outside the arrangement. We check the right to choose and the terms of the arrangement in the policy.

Downtime days

Operational damage that is not part of the assessment. It requires records of the downtime period and of the actual loss.

Third-party claims

Files that open and close without follow-up. Bringing them together allows one orderly move instead of individual requests.

Subrogation

A claim for reimbursement from the party responsible for the damage. In fleet files this is a significant source of recovery that is sometimes left unused.

Nationwide

Working with organizations across Israel

The office is in Tel Aviv and manages claims for companies and organizations from every region, with all insurers and in every court district.

Starting does not require an in-person meeting. A short call and a map of your existing insurance portfolio are enough to set a procedure.

Leonardo da Vinci 14, Tel Aviv · 077-444-7050

Gush Dan and the Center Logistics centers, vehicle fleets and offices
Sharon and Shfela Industrial zones, warehouses and garages
Jerusalem area Passenger transport and haulage companies
North and South Ports, terminals, industry and field fleets
Representative cases

Files that began with a reduction

Three representative cases from our ongoing dealings with insurers. The descriptions are general and do not identify any client.

Leasing

A reduction pattern that only showed up once files were combined

The situation

Each file on its own looked reasonable. Only when the events were combined did it become clear that the same deduction repeated across hundreds of claims.

What was done

Mapping the pattern against the policy wording allowed one orderly move instead of dozens of separate requests.

Haulage

A cargo claim denied outright

The situation

The denial relied on an exclusion in the commercial policy that did not fit the actual circumstances of the haulage.

What was done

The bills of lading and route records were set against the exclusion, and the file was sent back for a review on the merits.

Garages

Parts differences that had to be explained

The situation

Payments arrived according to the insurer's price list, with a consistent gap against the work actually done.

What was done

A systematic comparison between job cards and payments exposed the gap and put it up for discussion.

The descriptions are general and do not identify any file or client. The outcome of one case does not indicate the outcome of another.

FAQ

What counts as a business interruption loss?

+

The loss of income during the period in which the business is not operating, subject to the relevant policy annex.

The insurer claims underinsurance. What can be done?

+

The claim is checked against the sums insured that were set and the proposal form that was signed.

Should we appoint our own assessor?

+

Usually yes. A counter-assessment is a basis for an orderly discussion about the extent of the damage.

Business track

Bring claims management into one channel.

A short call, a map of your existing insurance portfolio, and an agreed working procedure.

Schedule a call
Further reading You received a denial letter. What now?→ Partial payment: where the gap opens→ Release and discharge form: what you are signing→